Showing posts with label cryptos. Show all posts

Friday, 5 June 2026

SHOTS FROM THE DOOR

STANDING AT THE ASYLUM DOOR TAKING PHOTOS

Living near a beach I often watch the waves and tides

And living in a lunatic asylum, the beach is a calming influence

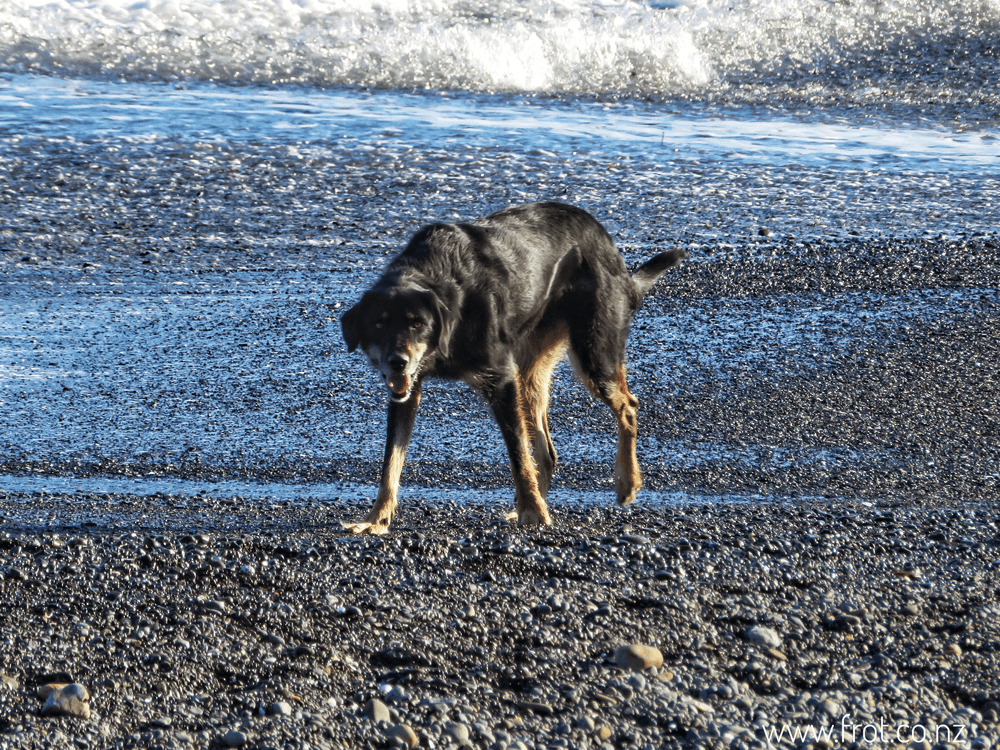
Despite being a cat person, I often like to watch the dogs at the beach. Unlike so many people now, they generally don’t wear muzzles.

Here is a photo of a dog I took while watching waves on the beach a couple of days ago.

Now I’m going to go on about cryptos.

People on Hive often seem to think that cryptos are a big and important concept that will change the world. And maybe one day they will.

But right now in the global economy, they are a drop in the ocean. And Hive is just a microscopic part of that drop.

I hear people talking about cryptos who clearly don’t understand that the corona plandemic is all a big psyop.

Which generally means they don’t grasp that the next stage of the plan is a full economic melt down.

Today I stood in town watching people walking past in muzzles, scanning their phones, and social distancing. “The new normal” – This is Lampton Quay, Wellington New Zealand, today.

image.png

I have no idea how things will be in five years – an Orwellian hell or a new global awakening. But right now our society is collapsing, and anyone who hasn’t noticed that yet, is living in a blue pilled fantasy.

image.png

When the tide is going out, sometimes a wave is bigger than the one before it. But ultimately the tide is going out. And right now, the tide of the global economy is going out.

I’m not talking about some distant possible future. Lambton Quay was once the second wealthiest inner city street in NZ, a country which was once considered one of the most affluent first world countries. It wasn’t exactly pumping today, and all those expensive shops will clearly be struggling to pay their bills with so few customers.

Right now this country is being systematically destroyed but the population is so mind controlled that most of them have no idea. I have previously tried to explain what the Agenda 2030 plan entails, but it’s like showing people chemtrails in the sky and having them literally unable to see what is right above their heads.

And the people who have had their graphine oxide injections now have to fight against seeing what is happening right in front of them, with everything they have. Because their sanity depends on it. Little do they realise how soon their delusion of sanity is going to implode.

In between prepping and doing my best to avoid most of the other inhabitants of the asylum, I sometimes watch the waves and try to remember that the sea will still be here long after we are all gone.

image.png

https://peakd.com/hive-150329/@frot/standing-at-the-asylum-door


 This content was previously posted on FROT, September 25, 2021

Thursday, 23 April 2026

WHAT IS Z-CASH?


Z-cash is a privacy coin that was launched in 2016. This is an unusually good description of how it works written by it’s founder, Zooko Wilcox, back in 2016.

This recently launched cryptocurrency has received attention for its enhanced privacy features. Zooko Wilcox, the project’s lead developer, explains how these features work and what they mean for policymakers.

Zcash is a cryptocurrency network that launched in October of 2016. Like other cryptocurrency networks (e.g. Bitcoin or Ethereum), Zcash allows anyone with a computer and an Internet connection to send and receive scarce tokens that can be used like cash on the Internet. 
 
The software that powers Zcash is directly derived from Bitcoin’s core software, but it has been modified in order to enhance user privacy.

The members of the network who relay, validate, and bundle user transactions into blocks are, like in Bitcoin, commonly called miners. These miners are rewarded for honest participation with transaction fees and newly minted Zcash, and they must solve a difficult math problem (similar but distinct from Bitcoin’s mining algorithm) in order to earn the privilege of participation. 

As with Bitcoin, anyone can be a miner on the Zcash network, all they need is an Internet connection, a reasonably powerful computer, and the free and open source Zcash software. Zcash is an open blockchain network.
Why launch a new cryptocurrency with enhanced privacy?

Bitcoin has been around for almost a decade, and by now many people have realized that it is not nearly as private or anonymous as many initially thought. 

That can be a good thing when it comes to catching criminals, but it can also be a bad thing for innocent users. In fact, Bitcoin’s current specifications make it almost impossible for an unsophisticated innocent user to have any privacy.

Here’s a simple example. Most people use bitcoin by sharing a payment address that looks something like this:

1CPwNACt62wts2yGbz1vUuqeGD58SzzeAL

Maybe that address belongs to a bartender. To accept bitcoin for cocktails the bartender puts that address on a poster behind the bar in the form of a QR code so it would look something like this (courtesy of Room77 in Berlin):


Patrons at the bar can take a picture of that code with their smartphone and use a bitcoin wallet app to pay that address for their drinks. Trouble is, anyone can look that address up in the Bitcoin blockchain and see every incoming transaction and the total amount of bitcoin sitting in that address. 

If we look up that information, then we have at least some idea of how rich the bartender is (good information for a would-be robber), and how successful the bar has been (good information for the competing bar next-door). 

Also, if we sat next to someone while they took a picture of the payment code with their phone, then we might have a good idea of how rich the customer next to us is as well by identifying the most recent incoming transaction for the bartender’s address and looking up the balance of the sending address, the customer’s address.

This poor privacy can be marginally improved by having your Bitcoin wallet generate a new payment address every time you want to be paid. So the bartender would now show each customer a new and different QR code to pay his or her individual tab. But the basic issue remains. 

Often those separate balances will be combined to fund an outgoing transaction. Perhaps the bartender wants to pay her rent with bitcoins she has received from patrons, but that single rent transaction is larger than any single payment from a patron. 

The bartender will need to use several of her receiving addresses to pay the rent, and all those addresses are then combined in a transaction message that ends up in the blockchain. 

By analyzing these transactions, a stranger who knows one of the bartender’s addresses can create a map of clustered addresses that are used by the bartender. 

So with clustering analysis, the stranger can still get a pretty good idea of the bartender’s net bitcoin worth, and learn all sorts of things about the bartender, like how much she pays in rent and how often.

To be truly private, a bitcoin user needs to take all kinds of technical precautions: never using the same payment address twice, avoiding recombining payment addresses as inputs for later transactions, sending funds to mixing services that will shuffle bitcoin balances amongst a bunch of other bitcoin users (and hopefully not run off with their money), using Tor or other private Internet services to make it harder to link geographic data from IP addresses to transaction messages; the list goes on. 

These are difficult steps for a technologically unsophisticated user to take, and even a sophisticated user might not take these steps if they aren’t doing anything criminal and feel that the benefits of privacy simply aren’t worth the costs.

As a result, Bitcoin as currently specified creates a perverse outcome: sophisticated criminals might be able to squeeze some anonymity out of the system, but your average innocent user gets no privacy whatsoever.
 
How is Zcash more private?

The Zcash network uses modified Bitcoin software to allow users a choice whenever they transact. You can get paid at a normal address that works transparently just like a Bitcoin address (we call this a transparent address, or “t-addr”) or you can use a private payment address (we call this a shielded address, or “z-addr”). If two people transact with shielded addresses, the Zcash blockchain will not record the details of that transaction publicly. 

All of those details are things that otherwise would be used to identify them: things like the amount of Zcash just sent and received and the addresses of the payor or payee. With Zcash shielded addresses, all of that information is encrypted or kept secret from the public.

Of course, that raises an important question. How do the users of the Zcash network know that no new money was created in a private transaction? How do we know that the sender did not just counterfeit new Zcash instead of sending you her existing balances? In Bitcoin you know that there has been no counterfeiting because the blockchain has an indelible record of all transactions that is complete with details like amount sent, sender address, and recipient address. 

That blockchain record goes all the way back to the beginning of the network, and if you sum up all the transactions you will get a number of Bitcoin in circulation that is only the amount of bitcoins legitimately mined so far mined. This gives us confidence that bitcoins are only being created according to the rules of the software; no fishy counterfeiting is taking place. So how can we be sure that there is no counterfeiting in Zcash if we cannot see all of the individual transaction records on the blockchain? This is where the new Zcash technology comes in.

Zcash uses cutting edge math and science to create a privacy protecting blockchain. Specifically, it uses cryptographic functions that are called zk-SNARKs. That stands for Zero-Knowledge Succinct Non-interactive Arguments of Knowledge. It’s a mouthful (computer scientists aren’t always the best at naming things), but what it means is this: with a zk-SNARK, a computer or network of computers can take some otherwise encrypted and unreadable data and prove certain limited facts are true about that data without revealing anything else about that data. 

So in the case of payments made to and from a shielded Zcash address, using a zk-SNARK built into the protocol software, the network can prove to any user that, on-net, all outgoing transactions equal all incoming transactions (i.e. no new money was created), but the zk-SNARK function proves it without revealing the specifics of those individual transactions, all the data that would be used to compromise your privacy.

Can regulated institutions use Zcash?

Financial institutions are legally required to comply with anti-money laundering and anti-terrorist financing laws and regulations. Can these institutions use a payment system and currency that leaves no record of individual transactions? Absolutely! That system is called cash and just about every financial institution in the world uses it. Cash transactions are still much more opaque than any cryptocurrency transaction, even a Zcash transaction from a shielded address.

If I go into a bank and hand the teller $1,000 worth of cash, the bank would have less information about that transaction—where I got the money in the first place—than if I sent them $1,000 worth of Zcash from a shielded address. At least with Zcash they know for sure that the money isn’t counterfeit. Just as financial institutions can accept and hold your cash without running afoul of the regulations, they can accept and hold Zcash as long as they continue to keep their own internal records as they are required to do by law.

The responsibility to comply with things like the Bank Secrecy Act (a financial surveillance law in the U.S.) is a responsibility borne by the institution and not by the technology behind the medium of exchange or the developers of that technology. 

We don’t ask the Federal Reserve to record all cash transactions, we ask that individual banks or money services businesses keep their own records, do their own Know-Your-Customer diligence, and reports things that look suspicious.

As we’ll see in the next section, financial institutions can implement compliance with Zcash, potentially even better than they can do with Bitcoin, because they can give regulators or (duly authorized, warrant-bearing) law enforcement privileged access to sensitive data in the blockchain. This approach to compliance is also arguably better than compliance using traditional pre-blockchain banking.

Does Zcash make regulation more difficult?

Zcash’s shielded addresses may make it more difficult for regulators and law enforcement to investigate using public data from the blockchain, but Zcash also has some built-in features that can help simplify regulatory compliance without compromising the privacy of innocent users. Two relevant technical concepts are view keys and memos.

Every shielded address comes with what we call a view key that is generated for the holder of the address. She can choose to share this view key with anyone else in the world. With that view key a person can get the details about the particular transactions sent from that address; they can see the recipient addresses and the amounts sent. Not only can they see these details, they can prove them with the certainty of a blockchain data structure.

(Note: at the time of this writing, the current version of Zcash — v1.0.3 — does not have complete support for users to retrieve and use view keys, even though they are effectively already included in the protocol.)

Accordingly, whenever the law demands transparency and whenever proper legal process is followed to obtain that transparency, a user or regulated firm can easily oblige by sharing the view key that un-blinds private transactions with the proper authorities. This is, in many ways, superior to the current state of affairs with Bitcoin where both law enforcement and the general public can see a wealth of private information about your Bitcoin addresses. 

It’s also better than the current state of affairs with pre-blockchain banking transactions because the data being shared can be verified by an open network of computers, rather than law enforcement needing to take the regulated party or the individual being questioned at their word.

Zcash transactions also have a memo field that can be used to send additional data about the transaction viewable only to the recipient. This memo could carry data between financial institutions wherever they are required by law to send that data along (e.g. the “travel rule” requirement in the Bank Secrecy Act).

Why is financial privacy technology important?

Ultimately we believe that personal privacy is necessary for core human values like dignity, intimacy, and ethics. Without privacy, people will often abstain from doing anything that is legal but also unpopular or politically incorrect. 

This chills free expression and leaves us with a less diverse and less resilient community. Leaked private financial data can also be used by businesses to discriminate against vulnerable populations, or people with a lot to lose. 

Data analytics technology is advancing rapidly and without financial privacy we run the risk of being dealt with or identified in business or even personal contexts as merely an amalgam of facts and figures, rather than as unique individuals with dignity.

Financial privacy is also essential in an institutional context. As large financial institutions like banks have begun investigating blockchain technology to streamline their business processes, one of the chief impediments has been the transparency inherent in a Bitcoin-like blockchain. 

When you trade and how much you trade is proprietary information that an institution like an investment bank would likely rather not share with their competitors. The zk-SNARK technology pioneered for Zcash might allow big firms to use blockchains as cost-saving infrastructure without forcing them to share that proprietary information.

At heart this is the core goal of Zcash, to build an open and trustworthy financial system that doesn’t put our privacy and freedom at risk.

https://www.coincenter.org/what-is-zcash/


Zooko Wilcox is Founder and CEO of the Zcash Electric Coin Company. He has more than 20 years of experience in open, decentralized systems, cryptography and information security, and startups. He is recognized for his work on DigiCash, Mojo Nation, ZRTP, “Zooko’s Triangle”, Tahoe-LAFS, BLAKE2, and SPHINCS.

https://www.frot.co.nz/design/wp-content/uploads/2020/05/www.frot_.co_.nz_.800.jpg
 
This content was previously posted on FROT, March 12, 2021 
 

Thursday, 9 April 2026

HAVE I TURNED INTO A SPINELESS GIMP?

 Like most people, sometimes I wake up in the night, soaked in sweat and freaking out that I have turned into a gimp.

For more than 20 years I’ve been researching “conspiracies” and posting stuff online that freaks out normies.

Most of my ex-friends think I’m a complete tool.

It’s one thing to write about complex webs of conspiracy that are quite theoretical when nobody really gives a toss anyway.

This week is different, and we have all tended to shut our pie holes and stop posting. Why? Because this week it either happens or it doesn’t and we are scared we will look like complete tools.

But everyone already thinks I’m a complete tool, so why am I acting like a gimp? (Gimps wear masks and say nothing while they wait patiently to be reamed by the man)

OK it’s time to grow a set and say what I think will happen before the end of this month. Either I will be right or wrong. And that is the nature of life.

image.png

LET’S SPIT IT ALL OUT RIGHT NOW. WHAT I AM PREDICTING FOR JANUARY:

All of the governments in Europe will collapse like a pack of cards into a stinking pile of their own corruption. The European Union will be over and out.

The American election will end in civil war, whoever is said to be president. America will rapidly move into a state of chaos.

The American economy will implode, and all assets will take a huge dive (especially shares). Yes that includes cryptos – all of them. After the initial panic fuelled drop, the assets I pick to recover this year are bullion and cryptos. That is why I’ve been saying to sell Bitcoin and buy back on the crash.

All economies globally are on the brink of bankruptcy after being hammered by the plandemic, and if America crashes the rest will follow right behind.

The world will appear to move close to a major war. Most likely USA vs. China. But this is all a script, and it’s like watching a Hollywood action movie. It’s all bullshit, just like coronavirus.

image.png

I haven’t been silent because I’m afraid to make those predictions, but because I don’t know what the ultimate outcome will be – great reset or great awakening?

This could go either way, and at this point all we can do is focus on the outcomes we want. Something I learned from bike racing is that we go exactly where we look. 

 Even when we are sliding along the road on our arse, the lamp post or the patch of grass are both equally available and we will inevitably hit the one we focus on. We have just lost traction and are about to bite the dust. Now it’s time to crash like a pro.

Shit is about to hit fans, so I’m going to close my mouth and focus on the great awaking option. Swallow the purple pill and take a ride on the wild side.

image.png

https://peakd.com/hive-167922/@frot/have-i-turned-into-a-spineless-gimp


 This content was previously posted on FROT January 19, 2021

Friday, 3 April 2026

WHAT THE FUCK IS DEFI?

OK , this is some next level crypto geek shit, and it’s as confusing as hell.

Two main things I want to know, can I make shitloads of money if I buy some, and can I use it to avoid globalist control?

I have no idea what I’m talking about so this post is more to help me understand it than to tell anyone else anything.

What is DEFI? – this webpage sounds like a start, but it’s way too long and boring for a simple cunt like me, so I’ll edit the fuck out of it:

https://www.coindesk.com/what-is-defi

DeFi is short for “decentralized finance”

It could potentially cut out the globalist banker leeches that are fucking us over. (Maybe)

Most applications that call themselves “DeFi” are built on top of Ethereum

That’s because Ethereum’ is set up for smart contracts – which automatically execute transactions if certain conditions are met.

With smart contracts at the core, dozens of DeFi applications are operating on Ethereum, and Ethereum 2.0, a coming upgrade to Ethereum, could give these apps a boost by improving Ethereum’s scalability issues.

The most popular types of DeFi applications include:

  • Decentralized exchanges (DEXs): Online exchanges help users exchange currencies for other currencies, whether U.S. dollars for bitcoin or ether for DAI. DEXs are a hot type of exchange, which connects users directly so they can trade cryptocurrencies with one another without trusting an intermediary with their money.
  • Stablecoins: A cryptocurrency that’s tied to an asset outside of cryptocurrency (the dollar or euro, for example) to stabilize the price.
  • Lending platforms: These platforms use smart contracts to replace intermediaries such as banks that manage lending in the middle.
  • “Wrapped” bitcoins (WBTC): A way of sending bitcoin to the Ethereum network so the bitcoin can be used directly in Ethereum’s DeFi system. WBTCs allow users to earn interest on the bitcoin they lend out via the decentralized lending platforms described above.
  • Prediction markets: Markets for betting on the outcome of future events, such as elections. The goal of DeFi versions of prediction markets is to offer the same functionality but without intermediaries.

In addition to these apps, new DeFi concepts have sprung up around them:

  • Yield farming: For knowledgeable traders who are willing to take on risk, there’s yield farming, where users scan through various DeFi tokens in search of opportunities for larger returns.
  • Liquidity mining: When DeFi applications entice users to their platform by giving them free tokens. This has been the buzziest form of yield farming yet.
  • Composability: DeFi apps are open source, meaning the code behind them is public for anyone to view. As such, these apps can be used to “compose” new apps with the code as building blocks.
  • Money lego: Putting the concept “composability” another way, DeFi apps are like Lego, DeFi apps can be similarly put together like “money lego” to build new financial products.

Lending platforms

Lending markets are one popular form of DeFi, which connects borrowers to lenders of cryptocurrencies.  One popular platform, Compound, allows users to borrow cryptocurrencies or offer their own loans. Users can make money off of interest for lending out their money. Compound sets the interest rates algorithmically, so if there’s higher demand to borrow a cryptocurrency, the interest rates will be pushed higher.

DeFi lending is collateral-based, meaning in order to take out a loan, a user needs to put up collateral – often ether, the token that powers Ethereum. That means users don’t give out their identity or associated credit score to take out a loan, which is how normal, non-DeFi loans operate.

Stablecoins

Another form of DeFi is the stablecoin. Stablecoins peg cryptocurrencies to non-cryptocurrencies, such as the U.S. dollar, in order to keep the price stable.

Prediction markets

One of the oldest DeFi applications  on Ethereum is a so-called “prediction market,” where users bet on the outcome of some event, such as an election.

The goal of the participants is to make money, though prediction markets can sometimes better predict outcomes than controlled methods, like polling. Centralized prediction markets with good track records in this regard include Intrade and PredictIt. DeFi has the potential to boost interest in prediction markets, which have traditionally been shut down by governments.

DeFi FAQ

How do I make money with DeFi?

The value locked up in Ethereum DeFi projects has been exploding, with many users reportedly making a lot of money.

Using Ethereum-based lending apps, as mentioned above, users can generate “passive income” by loaning out their money and generating interest from the loans.  Yield farming, described above, has the potential for even larger returns, but with larger risk. It allows for users to leverage the lending aspect of DeFi to put their crypto assets to work generating the best possible returns. However, these systems tend to be complex and often lack transparency.

Is investing in DeFi safe?

No, it’s risky. Many believe DeFi is the future of finance and that investing in the disruptive technology early could lead to massive gains.

But it’s difficult for newcomers to separate the good projects from the bad. And there has been plenty of bad.

As DeFi has increased in activity and popularity through 2020, many DeFi applications, such as meme coin YAM, have crashed and burned, sending the market capitalization from $60 million to $0 in 35 minutes. Other DeFi projects, including Hotdog and Pizza, faced the same fate, and many investors lost a lot of money.

In addition, DeFi bugs are unfortunately still very common. Smart contracts are powerful, but they can’t be changed once the rules are baked into the protocol, which often makes bugs permanent and thus increasing risk.

When will DeFi go mainstream?

While more and more people are being drawn to these DeFi applications, it’s hard to say where they’ll go. Much of that depends on who finds them useful and why. Many believe various DeFi projects have the potential to become the next Robinhood, drawing in hordes of new users by making financial applications more inclusive and open to those who don’t traditionally have access to such platforms.

This financial technology is new, experimental and isn’t without problems, especially with regard to security or scalability.

Developers hope to eventually rectify these problems. Ethereum 2.0 could tackle scalability concerns through a concept known as sharding, a way of splitting the underlying database into smaller pieces that are more manageable for individual users to run.

How will Ethereum 2.0 impact DeFi?

Ethereum 2.0 isn’t a panacea for all of DeFi’s issues, but it’s a start. Other protocols such as Raiden and TrueBit are also in the works to further tackle Ethereum’s scalability issues.

If and when these solutions fall into place, Ethereum’s DeFi experiments will have an even better chance of becoming real products, potentially even going mainstream.

Bitcoin as DeFi

While Ethereum is top dog in the DeFi world, many proponents of Bitcoin share the goal of cutting the middleman out of more complex financial transactions, and they’ve developed ways to do so using the Bitcoin protocol.

Companies such as DG Labs and Suredbits, are working on a Bitcoin DeFi technology called discreet log contracts (DLC). DLC offers a way to execute more complex financial contracts, such as derivatives, with the help of Bitcoin. One use case of DLC is to pay out bitcoin to someone only if certain future conditions are met, for example, betting on the outcome of a sports event.

Well that sort of makes sense, but I still don’t really get all this – first question – apart from Etherium, what other tokens are popular for Defi?

Chainlink (LINK)

Chainlink
$27.68

Tokens currently represent the vast majority of smart contract applications. Chainlink aims to bring the power of smart contracts to the real world.

Chainlink brings outside data into smart contracts. Ethereum Smart contracts can now act on other asset prices, global occurrences and make calls to other APIs. Chainlink makes smart contracts really smart.

It also incorporates real-world data. For example, it allows farmers to hedge against a bad season. The smart contracts filtered through Chainlink pay out insurance claims if values in the contract like share price, temperature or rainfall do not meet a certain standard. Instant payments deploy as soon as the program receives the appropriate weather data. Chainlink’s potential seems limitless and many of the top DeFi apps pay huge amounts for the LINK token to use their platform.

Uniswap (UNI)

Uniswap
$29.75

Uniswap is an Ethereum-based DApp for exchanging Ethereum tokens through liquidity pools. Uniswap provides 2 core products: providing and using liquidity.

Uniswap offers users the ability to exchange Ethereum-based cryptocurrencies instantly by tapping into its smart contract liquidity pools. These liquidity pools are filled by other users, who earn the exchange fees for providing liquidity.

Uniswap fees must be paid with the UNI token, making it one of Benzinga Crypto’s top picks for this market cycle.

Stellar Lumens (XLM)

Stellar
$0.381584

Stellar, a decentralized platform for uniting the world’s various banking systems, uses different, disconnected payment methods (ACH, SEPA, SPEI, etc). Stellar’s network connects these systems through a decentralized ledger, with on-off ramps for every payment method.

Stellar’s closest competitor, Ripple, faces SEC investigation. Stellar has a prime opportunity to seize the moment and take its best shot at becoming the global payment network.

To prevent spam on the Stellar Network, users must pay a transaction fee and meet a margin requirement in Stellar’s token, Lumens (XLM).

Aave (AAVE)

Aave
$364.52

Decentralized lending offers higher interest rates than centralized lending with better security and anonymity. Aave, one of the leading lending protocols around today, means borrowers must offer collateral greater than the amount they borrow into the loan smart contract. The smart contract safely holds collateral in escrow throughout the term of the loan, replacing the need for a trusted middleman.

Should the borrower default, the lender gets automatically paid by the smart contract.

Aave offers 10% APY for certain stablecoin loans with no know-your-customer (KYC) required, a product  unheard of in traditional finance.

https://www.benzinga.com/money/best-alt-coins/


 This content was previously posted on FROT January 9, 2021

FROT TOP 10 MOST POPULAR POSTS THIS MONTH